Make an enquiry
Let us know your needs and we’ll be in touch shortly.
Check out all the latest updates, insights and advice from our expert team.
A professional indemnity policy can respond to a negligence claim yet exclude losses connected with insolvency. Common exclusions in professional indemnity policies may also include deliberate wrongdoing, contractual liabilities beyond ordinary professional duties, employment disputes and work outside the activities declared to the insurer. The exact wording matters: an exclusion can affect whether a particular claim is covered, not just how much the policy pays.
It’s reasonable to expect professional indemnity cover for claims arising from advice or services, but not every related loss, penalty or legal cost is included. Government fines and statutory penalties are commonly excluded, while defence costs may reduce the available limit or be subject to the excess. Professional indemnity cover generally addresses financial loss, rather than third-party physical injury or property damage.
This guide explains how common exclusions work, why insolvency wording deserves particular attention, and how claims-made terms, notification requirements and defence costs can affect a claim. It also shows when to review your policy against the work your business actually carries out, so you can identify potential gaps and understand what your cover is designed to do.
Professional indemnity insurance is designed for claims involving alleged negligence or errors in professional advice or services. Government fines and statutory penalties are commonly excluded. These are among the common exclusions in professional indemnity policies, and can leave a business responsible for a penalty imposed after an investigation or regulatory decision.
The wording matters. An exclusion may refer to fines, penalties, punitive damages, or several categories together. Those terms can shape how the insurer treats a demand, even when the same matter also includes a client’s compensation claim. For example, a consultancy accused of faulty advice might face both a client’s financial-loss claim and a separate regulatory penalty. The policy may treat each part differently.
Separate the types of amounts claimed. Compensation sought by a client for a professional error may fall within the policy’s insuring clause, subject to its terms. A statutory penalty imposed on the business may be excluded. The claim’s label alone doesn’t settle the issue: the wording, alleged conduct and nature of each amount all matter.
Solicitors have a specific framework for the compulsory layer of professional indemnity insurance. According to the Solicitors Regulation Authority (SRA), its Minimum Terms and Conditions permit insurers to exclude certain fines and penalties. They also allow only a defined list of exclusions in that compulsory layer. The relevant wording and type of penalty determine how the clause applies.
Defence costs need separate attention. Some policies pay them in addition to the indemnity limit, preserving that limit for damages. Others include defence costs within the limit, leaving less available for a settlement or judgment. An excess may also apply, requiring the insured to contribute to defence costs. Legal expenses responding to a regulator could reduce the remaining cover if they are included within the limit.
Read the fines and penalties exclusion alongside the sections on defence costs, excesses and limits. Check whether the wording addresses regulatory investigations and legal representation, or only specified claim costs. This helps show how common exclusions in professional indemnity policies interact when one incident produces several types of loss.
For a business facing a complaint, preserve relevant advice, instructions, and correspondence, then notify the insurer as the policy requires. Some policy wording gives 7 days as an example of a strict notification timeframe. Prompt notice lets the insurer assess the claim and defence-cost obligations before costs build. It doesn’t make an excluded penalty covered, but can support the handling of covered elements.
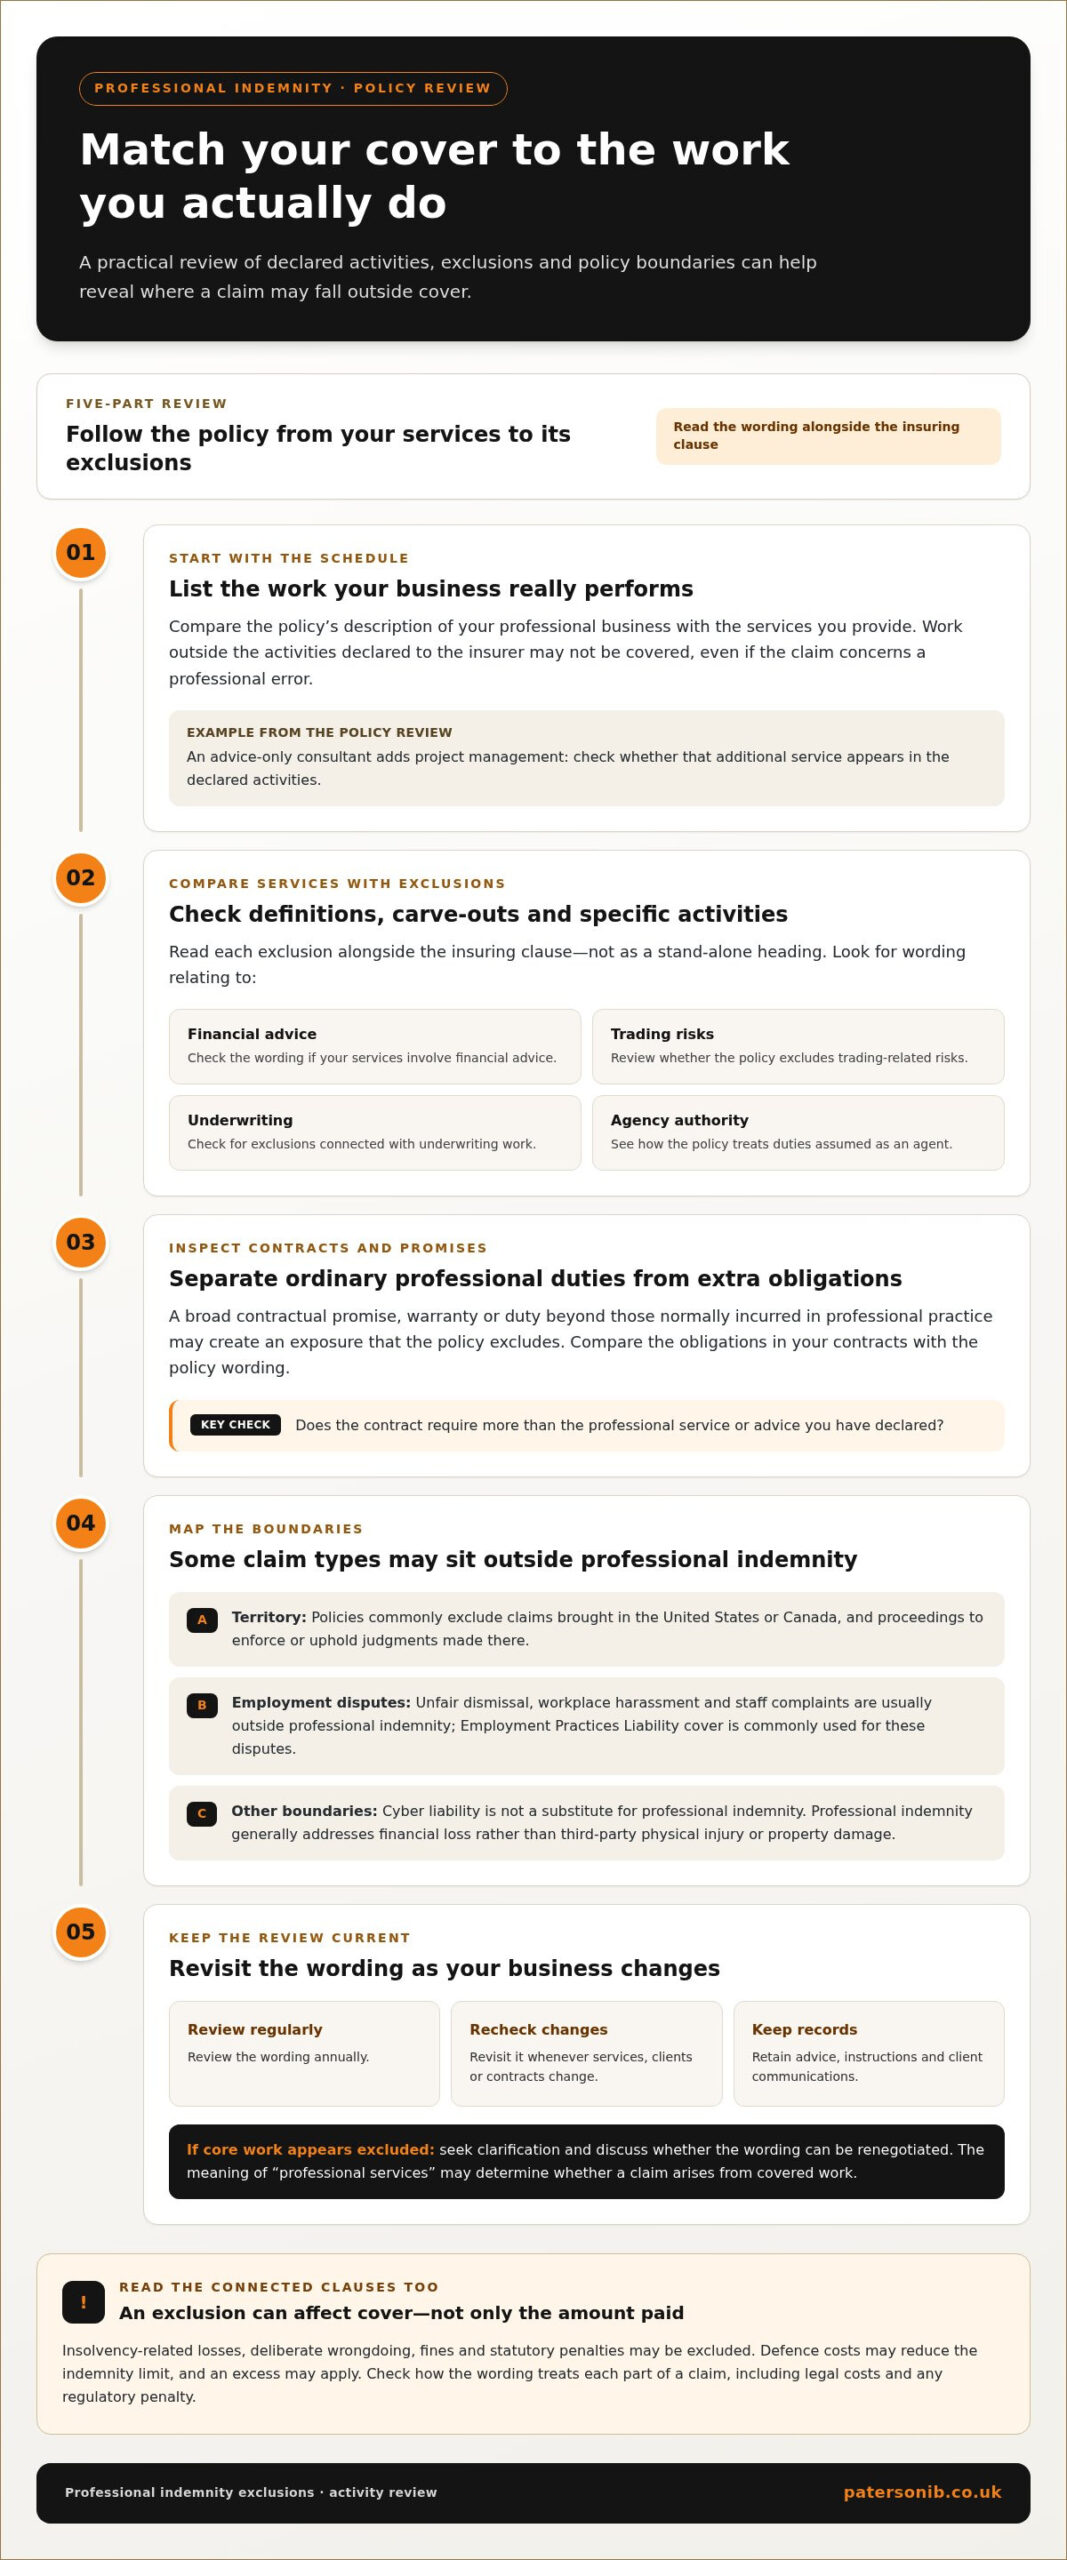
Professional indemnity exclusions vary between policies, so compare the wording with the work your business actually performs. A practical review looks at declared activities, excluded events and the claims that could arise from each service.
To match exclusions to your business activities, compare policy definitions and carve-outs with the services you provide. Work outside the activities declared to the insurer may not be covered, even if a client’s claim concerns a professional error.
Start with the description of your professional business in the schedule. For example, a consultant who adds project management to an advice-only practice should check whether that additional work appears in the declared activities. Then read each exclusion alongside the insuring clause, rather than treating a heading as a complete summary.
Look for exclusions relating to financial advice, trading risks, underwriting or agency authority. A firm that introduces clients to investments, for instance, should examine wording on financial services and any duties it assumes under a contract. Some policies also exclude obligations beyond those normally incurred in professional practice. A broad contractual promise may therefore create a different exposure from an ordinary professional duty.
Other clauses may focus on where claims are brought. Professional indemnity policies commonly exclude claims brought in the United States or Canada, and proceedings to enforce or uphold judgments made there. Businesses serving overseas clients should compare those territorial terms with their contracts and planned work. Employment disputes, including unfair dismissal, workplace harassment and staff complaints, are also usually outside professional indemnity cover. Employment Practices Liability cover is commonly used for those disputes.
Review the wording annually and whenever your services, clients or contracts change. Keep records of advice, instructions and client communications, then compare them with the declared activities. If an exclusion appears to remove work essential to your core business, seek clarification and discuss whether the wording can be renegotiated. Defined terms matter: the meaning of “professional services” may determine whether a claim arises from covered work.
Cyber incidents and data breaches are often treated separately from professional negligence claims. Professional indemnity insurance isn’t a substitute for cyber liability cover, so a business handling customer records should consider how each policy responds to a breach.
For example, a data breach could involve both an alleged failure in professional services and costs arising from compromised systems. Read the exclusions and definitions in both policies to understand which events and losses each addresses. The same careful distinction applies to intellectual property infringement: wording varies, and the policy’s response depends on the allegation, the professional activity and any relevant exclusion. Don’t assume every infringement claim is automatically included or excluded.
Check whether your work involves creating, adapting or using client-owned material, then compare those activities with the policy wording. A review of professional indemnity cover can help identify where declared services and exclusions need closer attention.
An insolvency exclusion may remove cover for claims arising from trading debts or a business collapse. The wording may apply when the insured becomes insolvent, or when a client’s failure causes the claimed loss. For professional indemnity insurance, the key distinction is whether the claim alleges a professional error or seeks recovery of debt created by insolvency. The policy clauses define how closely the loss must connect to the insolvency event.
Consider an adviser whose client collapses after receiving advice. If the claim alleges negligent advice that caused a separate financial loss, both the professional duty and the insolvency exclusion need careful review. If the claim simply seeks unpaid trading debts, the exclusion may be more directly relevant. The distinction matters because a claim can involve both an alleged service failure and losses arising from a company’s inability to pay.
The Commercial Court considered an insolvency exclusion in Crowden v QBE Insurance (Europe) Ltd, reported as [2017] EWHC 2597 (Comm). The case illustrates why courts examine the wording and the connection between the alleged loss and insolvency. It isn’t enough to see “insolvency” in an insurance policy and assume every claim connected with a failed business is treated alike. The clause’s scope and the claim’s actual basis remain important.
Are bodily injury and property damage excluded from professional indemnity cover in the UK? Professional indemnity insurance generally addresses financial loss from professional errors, not third-party physical injury or property damage. Public liability insurance is commonly used for those separate risks, such as a visitor injured at business premises.
Are claims between insured parties or related companies excluded under professional indemnity insurance? Related-party exclusions may restrict claims between insured businesses, but an associated-company clause can preserve indemnity or contribution for an independent third-party claim arising directly from a breach of professional duty. For example, a related company’s role in a dispute doesn’t automatically determine whether an independent client’s claim remains relevant.
What are the common territorial and jurisdiction exclusions in UK professional indemnity policies? Policies commonly exclude claims brought in the United States or Canada, and proceedings to enforce or uphold judgments made there. A UK business with overseas contracts should compare where claims may be brought with the policy’s territorial and jurisdiction clauses.
For a closer review, separate the claim into the alleged professional breach, the loss being claimed and any connection to insolvency. Then read the policy’s defined terms and exclusions together. A trading debt, an independent client’s negligence claim and a property-damage allegation raise different coverage questions, even when they stem from the same failed project. The practical lesson is to assess what the claimant seeks and why, rather than relying on the insolvency label alone.
Yes. Professional indemnity insurance doesn’t cover deliberate misconduct or fraud. The cover is intended for claims involving negligence or errors in professional advice and services, not losses caused by intentional wrongdoing. A policy’s dishonesty exclusion sets out how the insurer treats such conduct, including allegations against an individual professional.
An allegation isn’t the same as an established finding. For example, a client might accuse a consultant of deliberately concealing a material fact after a project loses money. The insurer must consider the policy wording and the facts alleged when assessing the claim. The distinction between an honest mistake and intentional deception matters because negligence may fall within the policy’s purpose, while fraud is excluded.
For a firm, the position can be more nuanced than the conduct of one employee. Under the SRA Minimum Terms and Conditions, the permitted dishonesty exclusion cannot be used to deny cover to an innocent principal or the firm as a whole because one individual was dishonest. That protection applies to the compulsory layer of solicitors’ professional indemnity insurance. The SRA MTC also restricts insurers to a defined list of exclusions in that layer.
Consider a solicitor accused of misusing client funds while colleagues continued their work honestly. The alleged wrongdoer’s conduct and the firm’s potential liability aren’t necessarily treated the same way. The MTC rule prevents the permitted dishonesty exclusion from automatically removing compulsory-layer cover from an innocent principal or the entire firm. It doesn’t erase the allegation or make the dishonest individual’s conduct covered.
For businesses outside that specific solicitors’ framework, the policy wording remains central. Read the dishonesty exclusion for the people it applies to, the conduct it describes, and whether it addresses the insured individually or collectively. A clause may also distinguish between an allegation and conduct established through a final judgment or admission. Those details can affect how a claim is handled.
At renewal, compare the dishonesty wording with your business structure and the people insured. For example, check whether the schedule names individual professionals, a company, or both, then read how the exclusion refers to each. Keep clear records of advice, instructions, approvals and client communications. If a complaint alleges fraud, preserve relevant documents and follow the policy’s notification conditions rather than making assumptions about cover.
The practical distinction is straightforward: a professional error and deliberate deception are different types of conduct. An allegation of dishonesty may raise questions about the individual’s protection and the firm’s response, while the SRA MTC gives specific protection to innocent principals in the compulsory solicitors’ layer. For other policies, the exclusion’s exact scope determines how those distinctions apply.
Professional indemnity insurance is intended to respond to claims involving professional negligence or errors. A contractual liability exclusion may restrict cover where a contract makes the insured responsible for more than ordinary professional duties. The key question is whether the alleged loss would still create liability without that extra promise. Read the contract and policy wording together, because their terms define the obligation and how it is treated.
For example, a consultant may agree to provide competent advice, then separately promise a particular financial result. If the client claims the consultant failed to meet that guarantee, the claim may involve liability assumed under the contract rather than negligence alone. The policy may not cover that additional obligation. This distinction can matter even when the client’s complaint also refers to errors in the advice.
A revenue warranty shows the risk clearly. A consultant who guarantees a 50% revenue increase may assume liability beyond standard professional indemnity cover. If the client’s revenue doesn’t rise by that amount, the contract may give the client a claim based on the promise itself. That does not automatically establish a covered professional error. The policy’s contractual liability wording and the basis of the claim must be considered.
Construction contracts need particular attention to clause references. The policy may exclude liabilities assumed under JCT contract clauses 21.2.1 or 6.5.1, or clauses with similar intent or purpose. Check the exact clause numbers and wording in the signed contract, then compare them with the insurance exclusion. Similar-purpose wording can matter even when a contract uses different numbering.
Before signing a contract, identify any promise that goes beyond the service’s professional standard. Look for guaranteed outcomes, indemnities, warranties or commitments to accept another party’s liability. For each term, consider what loss it could create and whether the policy exclusion addresses that obligation. Keep the signed contract, amendments and relevant advice together, so the basis of a later claim can be understood.
Warranties can also appear in project documents rather than the main services agreement. For example, a consultant might sign a collateral warranty for a third party, creating obligations that differ from the original client contract. Compare each document’s duties with the policy wording, and don’t assume the original insurance description covers every later undertaking. The wording, insured activity and liability being claimed all shape the analysis.
A sound review focuses on the liability created by each promise, not just the document’s title. If a proposed contract includes a revenue guarantee or JCT clause 21.2.1 or 6.5.1, review its effect against the policy before accepting it. Discuss your professional indemnity cover in light of the contractual commitments your work requires.
Paterson Insurance Brokers helps construction businesses consider how their insurance fits the work they undertake. Construction Insurance is relevant when projects, contracts or services create risks beyond professional advice alone. Reviewing policy exclusions alongside actual site activities and contractual duties can help clarify where different covers may respond.
For example, a construction professional’s policy may treat design advice differently from physical injury or property damage risks. Reviewing the scope of your work and contract terms helps identify where exclusions need closer attention. Paterson Insurance Brokers also provides Agriculture Insurance, Retail & Wholesale Insurance and Manufacturing Insurance for businesses in those sectors.
If your construction activities or contracts have changed, make an enquiry with Paterson Insurance Brokers to discuss your insurance needs.
Your next policy review is an opportunity to match cover to the business you’re building, not just the work you’ve already completed. Before renewing or accepting a new contract, consider whether your services, client commitments and risk profile have changed. Keep a clear record of new activities and contractual promises so they can be considered alongside your policy wording.
Understanding the common exclusions in professional indemnity policies is useful, but applying them to your actual work helps reveal potential gaps. Paterson Insurance Brokers can discuss how your business activities relate to your insurance needs, including where construction, agriculture or retail and wholesale work forms part of your operation.
For a considered conversation about your cover, contact Paterson Insurance Brokers. A thoughtful review can help you approach future work with a clearer understanding of the protection in place.
Common exclusions include deliberate fraud, some contractual liabilities, insolvency-related losses, employment disputes and work outside the activities covered by the policy. Cyber incidents and data breaches may need separate cyber cover, while physical injury and property damage generally sit outside professional indemnity. Territorial wording may also exclude claims brought in the United States or Canada. Check the policy schedule and exclusions against the services and contracts your business actually has.
Government fines and statutory penalties are commonly excluded, but the policy wording determines how each amount is treated. The SRA Minimum Terms and Conditions permit insurers to exclude certain fines and penalties. Don’t assume punitive damages are treated identically to statutory fines: check the policy’s definitions and exclusions, and distinguish the penalty from any compensation or defence costs arising from the same matter.
Compare the schedule, insuring clause and exclusions with your current services, contracts and planned work. Mark any clause that appears to remove cover for a core activity, then discuss with your broker whether its scope can be clarified, narrowed or bought back. Negotiation depends on the insurer’s terms. Treat a change as effective only when revised wording or an endorsement is issued in writing, and keep it with the policy documents.
A claim may be excluded if the policyholder knew of a potential issue before cover began and did not disclose it. A retroactive date can limit cover for advice or work done before that date. Under claims-made cover, a valid policy must also be in force when the claim is made.
Let us know your needs and we’ll be in touch shortly.