Make an enquiry
Let us know your needs and we’ll be in touch shortly.
Check out all the latest updates, insights and advice from our expert team.
Specialist brokers may charge a client fee when the work involved calls for tailored research, advice or support beyond a straightforward transaction. Building a business case for specialist broker fees means weighing that service against how the broker is paid and what value their involvement brings. For UK mortgage advice, the Financial Conduct Authority’s MCOB 4.4A rules require brokers to disclose the basis of their remuneration, including client fees and lender commission, before making a recommendation.
It’s reasonable to question a fee, especially when another broker says their service is fee-free. But “fee-free” does not always mean no payment is involved: a broker may receive commission from a lender. The important comparison is the total cost, the work included and whether the payment structure suits your circumstances.
This guide explains why brokers charge, how fixed, percentage-based and commission-funded arrangements differ, and what clear fee disclosure should cover. You’ll also see how to assess whether a charge is proportionate to the complexity of your finance needs, so you can make a considered decision based on more than the headline fee.
Building a business case for specialist broker fees starts with connecting the charge to the work involved. A broker may assess a business’s funding position, identify relevant lenders and organise a complex application. This takes time and judgement, particularly when the company’s circumstances do not fit a standard lending route.
For a funding budget, record the broker’s fee, any lender commission, payment timing and agreed tasks. Building a business case for specialist broker fees means showing decision-makers what the business receives for each payment, rather than treating a fee-free label as proof of lower cost.
This video outlines how a commercial finance broker’s work can support a funding decision:
In mortgage lending, a broker may receive a procuration fee from a lender when the mortgage completes. The lender and product type affect the commission. This payment can fund the broker’s work without a separate client charge, while another arrangement may charge the borrower directly. Some brokers receive both, so the total remuneration matters more than the label.
A specialist broker may be useful when a business needs lenders with particular criteria or help presenting an unusual funding case. A high-street lender can be suitable when its standard criteria fit the business. Neither route always costs less or produces a better result. What matters is whether the adviser’s work suits the case and the proposed funding meets the business’s needs.
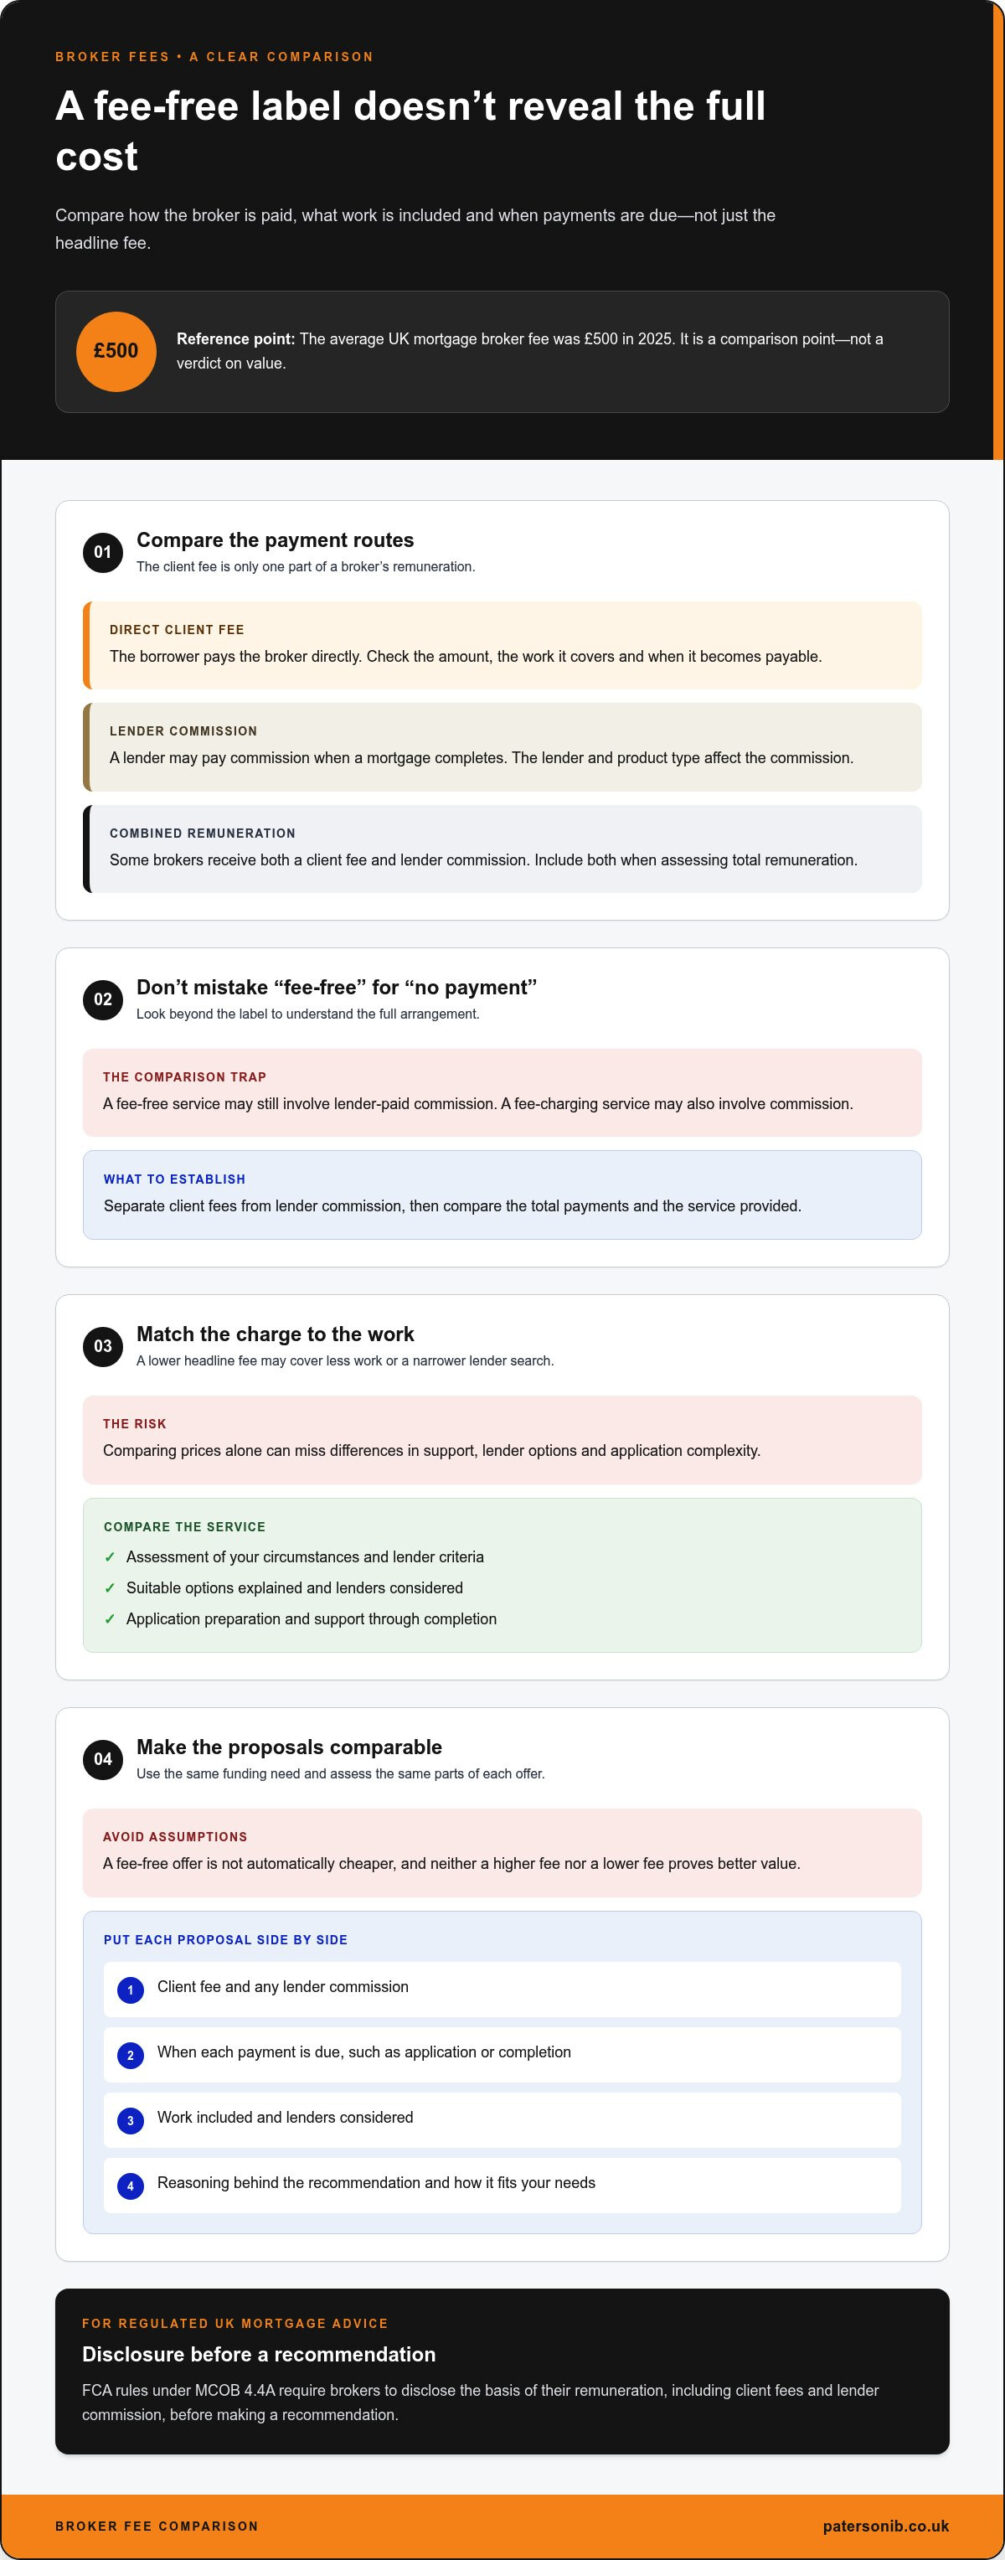
According to the Financial Conduct Authority, UK mortgage brokers must disclose their fees and lender commissions before making a mortgage recommendation under MCOB 4.4A of the FCA Handbook. Use that information to understand how the adviser is paid, what the proposed service covers and when charges become payable.
To assess value, connect the broker’s tasks to the funding decision. Note whether the adviser will interpret lender criteria, shape the application or explain a lender’s response. Then compare that support with the business’s internal capacity and the work involved in approaching lenders directly. This makes building a business case for specialist broker fees a reasoned assessment of the service, remuneration and business need.
A fee-free label describes the client charge, not necessarily the broker’s full remuneration. In mortgage advice, a lender may pay commission when a mortgage completes, while another broker may charge the borrower directly. Some arrangements combine both. Compare all payments, then assess the service and lenders considered for your circumstances.
The average UK mortgage broker fee was £500 in 2025 in the comparison reported for this topic. That figure is a reference point, not a verdict on value. The difference depends on the work involved, the complexity of the application and what support the charge covers.
Compare proposals on the same basis. Record the client charge, any lender commission, when each payment is due and the work included. Then consider whether the broker will assess your circumstances, explain suitable options, prepare the application and support it through to completion. A lower charge may not be better if it covers less work or a narrower lender search.
Interest matters too, but a broker’s fee should not be judged by the interest rate alone. For example, a business comparing two mortgage offers should consider the overall borrowing terms and the broker’s total remuneration. A fee-free option may still involve lender commission; a fee-charging option may provide a different service or access to different lenders. Compare actual offers and charges, not assumptions based on the label.
Use these steps to create a clear comparison for your funding decision:
For a business case, explain why the selected service fits the funding requirement. Link each payment to defined work, such as assessing lender criteria or presenting the application. This helps decision-makers weigh the broker’s charge alongside interest and other borrowing payments, rather than assuming a fee-free offer is automatically cheaper.
Finally, compare like with like: the same funding need, similar lender options and clearly described support. If one proposal costs more, identify the additional work or access that accounts for the difference. This gives the business a practical basis for choosing between a direct fee, commission-funded advice or a combined arrangement.
Clear disclosure helps a business assess broker charges against the proposed work and funding route. For a regulated mortgage, the timing and content of remuneration disclosures matter.
A specialist broker may charge an upfront or non-refundable fee when the business agrees to those terms for defined work. Before paying, review the engagement terms for the amount, payment date, services covered and circumstances affecting refunds.
For example, a complex case may involve reviewing income, accounts or a property valuation before an application. Ask how the upfront charge relates to those tasks and whether later work or completion support attracts separate payments. Record the agreed terms in the funding budget so decision-makers can see when cash leaves the business.
Businesses should look beyond the headline charge for separate costs, including lender fees, valuation costs, legal work and interest. These are distinct from the broker’s remuneration, so list each item separately and note when it may become payable.
Also assess the risk of paying for work that does not lead to funding. The agreement should explain the broker’s scope, payment stages, cancellation terms and any conditions attached to a non-refundable charge. In a complex case, unclear responsibilities can leave gaps between the broker’s work and tasks handled by lenders or other advisers.
According to the Financial Conduct Authority, UK mortgage brokers must disclose their fees and lender commissions before making a mortgage recommendation under MCOB 4.4A of the FCA Handbook. For applicable MCD-regulated mortgages, FCA rules also address disclosure of intermediary commission before application.
Use these disclosures to build a transparent comparison. Note whether remuneration comes from the business, lender commission or both, then record the payment timing and service attached to each amount. This distinguishes the broker’s charge from the lender’s costs and makes the funding case easier to review.
A practical review can follow these steps:
For a typical mortgage recommendation, disclosure before the recommendation helps the business assess the full remuneration structure. If the proposal involves a regulated mortgage, keep the FCA disclosure with the funding records. This creates a clear audit trail and helps decision-makers weigh the broker’s work against the total borrowing cost.
Broker charges can be fixed, tied to the mortgage amount, funded by commission or combined. Compare how each structure affects the total payable and the broker’s work.
A fixed fee sets the client charge in advance, regardless of the mortgage size. The agreed amount can make budgeting straightforward, but its value depends on the service and case complexity.
Check what the fixed charge covers, such as assessing lender criteria, preparing an application or providing support through completion. Establish when it becomes payable and whether additional work carries a separate charge. A fixed fee is easier to compare across proposals when each broker describes the same tasks.
A percentage-based charge rises or falls with the mortgage amount. An illustrative range for these charges is 0.35% to 1% of the mortgage.
This structure links the broker’s fee to the borrowing amount, not necessarily to the hours worked or case complexity. Assess the calculation against the service, lender options and criteria considered. Confirm which mortgage amount the percentage applies to and whether the charge is payable at application, offer or completion.
With commission-funded advice, a lender pays the broker after a mortgage completes. The business may pay no separate broker fee, but commission remains part of the remuneration arrangement. Ask for the amount or basis of commission and whether the broker also charges the borrower.
Commission can vary with the lender and mortgage product. Compare the proposed mortgage and its terms rather than assuming commission-funded advice is automatically cheaper. A clear breakdown shows how the broker is paid and whether different arrangements affect the recommendation.
Some brokers combine a client charge with lender commission. For a fair comparison, record the client fee, commission basis, payment timing and included work for each proposal. Keep the figures separate in the funding budget, then compare the total cost with the service provided.
A specialist broker fee should correspond to defined work, not an unclear promise of support. For a business finance application, that work may start with reviewing the company’s objectives, trading position and funding requirement. The agreement should explain which tasks the charge covers and where the broker’s role ends.
For example, a broker may assess the business information provided and identify lenders whose criteria appear relevant. This can help shape an application around the finance need, rather than sending the same material to every lender. Ask how the broker will present the case and what information they need from directors or finance staff.
Comparing funding routes may also be part of the service. A business seeking finance for equipment, expansion or cash flow has different requirements in each case. The broker’s work might include explaining suitable options, outlining key terms and discussing how repayment obligations fit the company’s plans. Check that the comparisons address the business’s actual objective.
Application preparation is another practical area to define. Clarify whether the broker will organise documents, complete application forms, explain lender questions and coordinate information through submission. Confirm who will gather financial records and respond if a lender requests more detail. Clear responsibilities reduce duplicated work.
Some agreements include communication with lenders after submission. Establish whether the broker will relay updates, help clarify requests and explain the next steps towards a decision or completion. Identify whether support ends at submission, at an offer or at another agreed stage. Those boundaries can affect the service’s usefulness if a case becomes more involved.
Use a scope checklist before approving a fee:
Then match each task to the fee structure and payment point. If a broker charges for an initial assessment, establish what deliverable follows. If the fee covers ongoing support, set out the included stages and any exclusions. A written scope gives directors a clearer basis for assessing value against the service received.
Businesses should distinguish broker work from other professional advice. A broker may help present a funding application, while accounting, legal or valuation work can involve separate professionals and costs. Keep those responsibilities distinct in the funding plan, especially when a lender requires additional information.
If arranging finance has prompted a review of wider business risks, discuss your business risk priorities as part of the planning process.
Paterson Insurance Brokers provides Construction Insurance for businesses seeking cover suited to their construction activities and risks. If a funding decision accompanies a new project, expansion or changing operations, reviewing insurance needs can form part of responsible business planning. Insurance cover is separate from finance broker fees, but both matter when planning for risk and operational commitments.
Paterson Insurance Brokers also supports businesses in agriculture, retail and wholesale, and manufacturing through sector-specific insurance. For construction firms, a conversation about Construction Insurance can help clarify how insurance fits the business’s circumstances and risk profile. Contact Paterson Insurance Brokers to discuss your business’s insurance needs, or visit patersonib.co.uk.
Use your funding decision as a prompt to review how planned activity may affect your business’s risk profile. Building a business case for specialist broker fees is one part of sound planning; understanding risks connected with growth, new projects or changing operations helps complete the wider picture.
Paterson Insurance Brokers provides Construction Insurance, Agriculture Insurance, and Retail & Wholesale Insurance. If your plans involve work in one of these sectors, consider whether your existing insurance arrangements reflect the business you are preparing to run. A measured review can help identify the right questions before commitments are made.
For a direct conversation about business insurance, contact Paterson Insurance Brokers. Take the next step at a pace that suits your business, with a clearer view of the decisions ahead.
A broker fee may be worthwhile if the service helps address a specific funding challenge. For example, a business with several income streams may value help presenting its finances clearly to lenders. Compare the fee with the work promised, options explored and terms offered. If your application is straightforward, extensive specialist support may add less value. Base your decision on the needs of the particular case.
UK specialist brokers may use a fixed client fee, a percentage of the borrowing, lender commission or a combination. A fixed fee is agreed for defined work; a percentage charge depends on the finance amount. Commission is paid by a lender under its arrangement with the broker. Ask for a written breakdown showing each payment, how it is calculated, when it is due and what work it covers.
Compare the service and funding terms, not just the fee label. A mainstream broker may suit a familiar application, while a specialist broker may be relevant when a business’s circumstances need closer assessment. A direct application avoids a separate broker service, but the business handles lender research and submissions itself. Compare the same borrowing need across routes, including interest, lender criteria, time required and any broker payment.
Look for case-specific evidence, not general claims about approval rates. A useful explanation should show which lenders were considered, how their criteria matched the business and why the proposed application fits. Ask for a clear comparison of available terms and the factors behind the recommendation. For example, a broker should be able to explain how the company’s trading history or income presentation shaped the funding options assessed.
Compare the broker’s total charge with the financial difference between the recommended funding and a suitable alternative. Include interest, lender charges and repayment terms, then consider the value of time spent preparing applications. Use actual offers and agreed fees rather than assumed savings. If the broker identifies a suitable route the business had not considered, record that benefit separately from cash savings.
For UK mortgage recommendations, the Financial Conduct Authority says brokers must disclose fees and lender commissions before making a recommendation under MCOB 4.4A. For applicable MCD-regulated mortgages, FCA rules also address intermediary commission disclosure before application. These mortgage requirements should not be treated as a universal rule for every type of business finance. Read the broker’s written terms and record your agreement to the charges and service.
Ask what tasks the fee covers, when payment is due and whether commission is also payable. Clarify what happens if the application changes, is withdrawn or does not proceed. Ask which lenders and funding routes will be assessed, what documents the business must supply and how updates will be handled. Finally, request a written scope and payment breakdown so directors can review the commitment before agreeing.
Let us know your needs and we’ll be in touch shortly.