Make an enquiry
Let us know your needs and we’ll be in touch shortly.
Check out all the latest updates, insights and advice from our expert team.
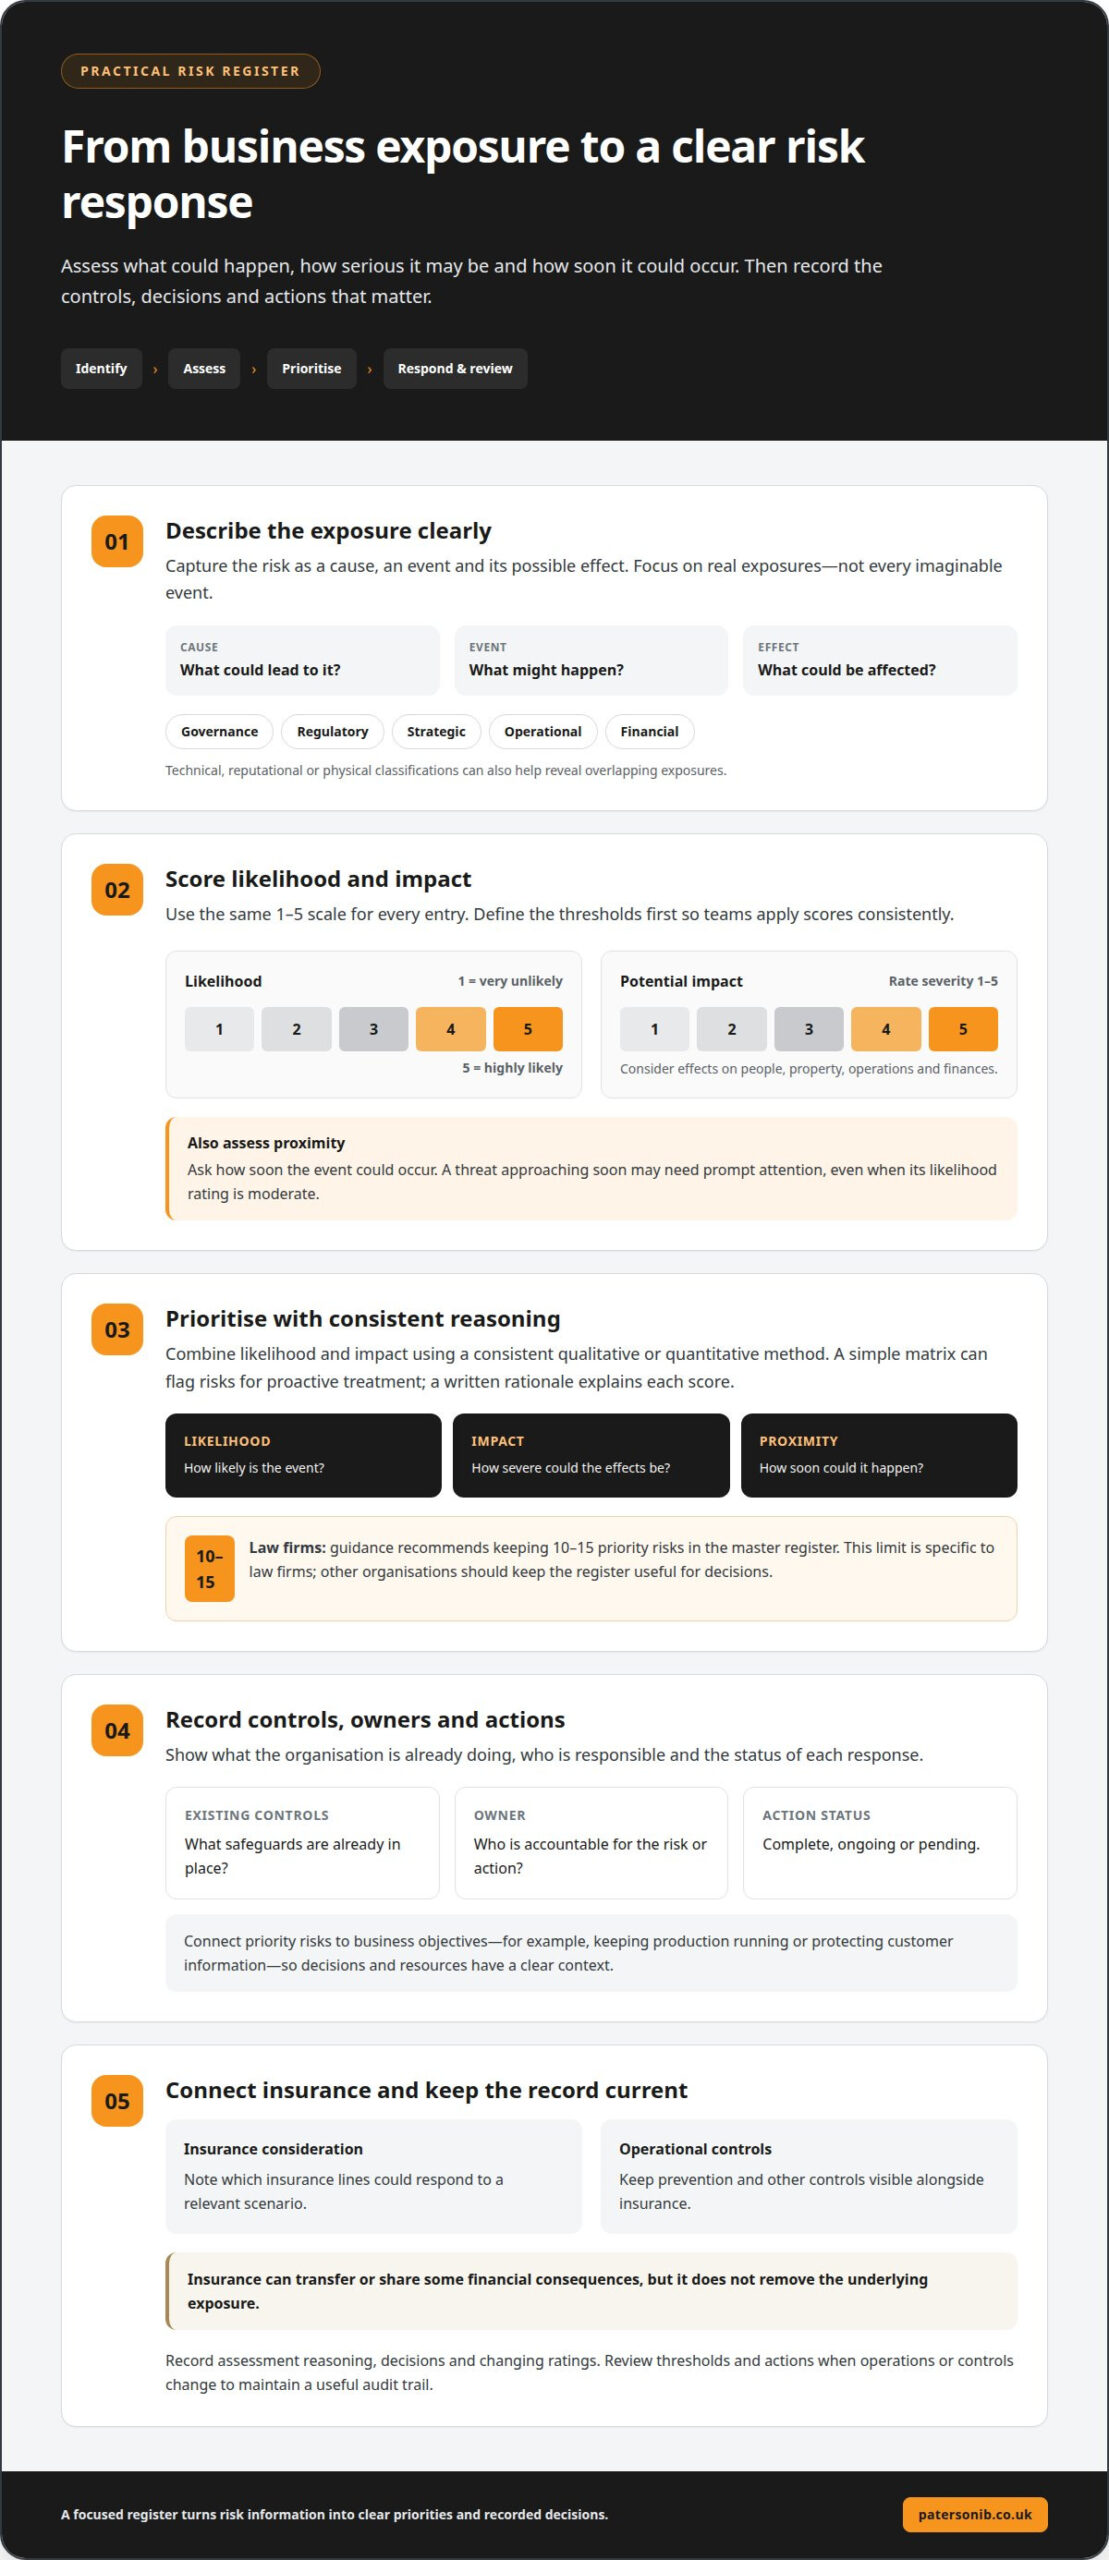
A useful risk register isn’t a catalogue of everything that could go wrong. It’s a focused record of which risks matter, what the business is doing about them and where insurance may fit. Creating a risk register for insurance purposes means connecting real business exposures with their likelihood, potential impact, existing controls and response actions.
It’s easy to see why this can feel like a paperwork exercise, especially when risks cross teams or affect several parts of the business. A clear register makes the information more practical: it helps prioritise attention, assign responsibility and keep a record of decisions as circumstances change. This guide explains how to identify and assess risks using a simple 1-5 scale, record owners and actions, consider insurance alongside other controls, and maintain an audit trail through regular reviews.
A risk register records business risks, their ratings and planned responses. It helps professionals compare exposures and guide action, rather than predict every possible event.
Assess each risk using a consistent likelihood scale from 1 to 5: 1 means very unlikely and 5 means highly likely. Rate potential severity from 1 to 5, considering effects on people, property, operations and finances. For example, machinery failure could interrupt production, damage equipment and cause injury. Also assess proximity: how soon could the event occur? A threat approaching soon may need prompt attention, even if its likelihood rating is moderate.
Define what each score means before comparing entries, so different teams use the same thresholds. For likelihood, describe the circumstances that distinguish very unlikely from highly likely. For impact, explain the disruption or harm represented by each score. Use business objectives and available evidence to set these benchmarks. Don’t assign high, medium or low labels arbitrarily. Record the reasoning and revisit the thresholds when operations or controls change.
Professionals connect risk management to an organisation’s objectives, then identify exposures across its operations and relationships.
Group risks by governance, regulatory, strategic, operational and financial themes. A second classification, such as technical, reputational or physical, can reveal overlapping exposures. For example, a supplier failure may cause operational disruption and financial loss. Professionals examine business activities, existing controls and changes to identify distinct risks, rather than listing the same event under several labels. This keeps the register organised and useful for decisions.
Map important suppliers, dependencies and the consequences of an interruption. A specialist component with no practical substitute could threaten production, while a delayed delivery might affect customer commitments. Assess related financial risks, including cash-flow pressure, fraud and changing costs. For each exposure, record its cause, possible event and effect. This helps distinguish a supplier issue from its wider operational or financial consequences.
Rank risks using their likelihood, impact and proximity, then consider existing controls and strategic objectives. A severe event approaching soon may deserve attention before a more distant, lower-impact issue. For a law firm’s master risk register or departmental subset, guidance recommends keeping 10-15 priority risks. This limit applies specifically to law firms; other organisations should make the register useful for decisions rather than attempt to record every possibility.
Consider whether the right people, skills and processes are available for critical work. In a professional services organisation, a shortage of experienced staff could delay work, weaken reviews or increase errors. Record the trigger, affected activity and potential consequences, then note existing safeguards. Consider whether workload allocation, supervision or a process change could reduce exposure. This links resource pressures to operational and reputational risks.
A structured risk management review can help connect these priorities with practical controls and insurance considerations.
A poorly built register can hide important exposures, misdirect responses and give a misleading picture in insurance discussions. Vague entries, missing owners or outdated actions make it harder to understand how risks affect business objectives.
Paterson Insurance Brokers offers Risk Management Consultancy to help businesses assess exposures, strengthen operational safety and consider how insurance fits their risk response. It can be a useful next step when your register needs a clearer connection between business risks, practical controls and cover.
Sector-specific context matters. A construction business may need to consider site and project exposures, while an agricultural operation faces different operational risks. Retail and wholesale businesses also have distinct premises, stock and trading considerations. Paterson Insurance Brokers can discuss these risks alongside relevant Construction Insurance, Agriculture Insurance or Retail & Wholesale Insurance.
For a considered conversation about your business risks and insurance needs, contact Paterson Insurance Brokers.
Treat the register as a starting point for a focused insurance discussion, not a document separate from daily decisions. New work, supplier changes or equipment investment can shift which exposures deserve attention. A professional review can connect the risk picture to the decisions ahead.
Consider upcoming changes and the questions they raise: which disruptions would be hardest to absorb, where controls rely on people or systems, and which financial consequences need attention? This gives the discussion practical context without assuming every exposure belongs in an insurance policy. Paterson Insurance Brokers’ Construction Insurance, Agriculture Insurance and Retail & Wholesale Insurance can be considered alongside Risk Management Consultancy where relevant.
A considered approach to creating a risk register for insurance purposes keeps risk discussions connected to changing business needs. Contact Paterson Insurance Brokers to discuss your risk management and insurance needs. A clear next step can help you approach future decisions with greater confidence.
A useful insurance risk register includes enough detail to support decisions about an exposure, its controls and its potential insurance relevance. Alongside risk descriptions and ratings, record affected business activities, the evidence behind assessments, policy lines considered and outstanding questions. For example, noting a key contract’s renewal date can prompt a timely review if responsibilities or business activities change.
A risk register is a working record that helps a business understand and manage uncertainty affecting its activities. For insurance discussions, it can connect a scenario, such as a customer complaint or equipment breakdown, with possible financial consequences and existing safeguards. This gives decision-makers a structured basis for deciding which exposures need further attention and how insurance fits into the wider response.
Include a clear risk description, its business context, assessment rationale, existing controls and planned response. Record the person overseeing it, action progress and review history. Add relevant insurance considerations, such as the policy line that may relate to the scenario and questions for discussion. For example, an entry about a data incident could distinguish recovery costs from interruption to normal operations.
A professional builds an understanding of how the organisation works through discussions with relevant staff and information about its activities, assets and dependencies. They examine how a change, failure or incident could affect business objectives. For example, a new sales channel may introduce different customer, technology or delivery exposures. The assessment then considers the circumstances and consequences of each distinct scenario.
Apply the register’s agreed scoring definitions consistently, using a five-point scale for likelihood and impact if that method has been selected. Consider the scores together through a matrix or another documented approach to indicate exposure. There is no single calculation method that suits every business; what matters is keeping the method and reasoning clear across entries.
A named person should oversee each risk, while the appropriate manager or leadership group maintains the register as a whole. The risk owner monitors changes; an action owner carries out a specific control or response. For example, an operations manager could own a machinery risk while a maintenance lead completes an agreed action. Clear responsibility helps prevent entries from becoming outdated or unattended.
Let us know your needs and we’ll be in touch shortly.